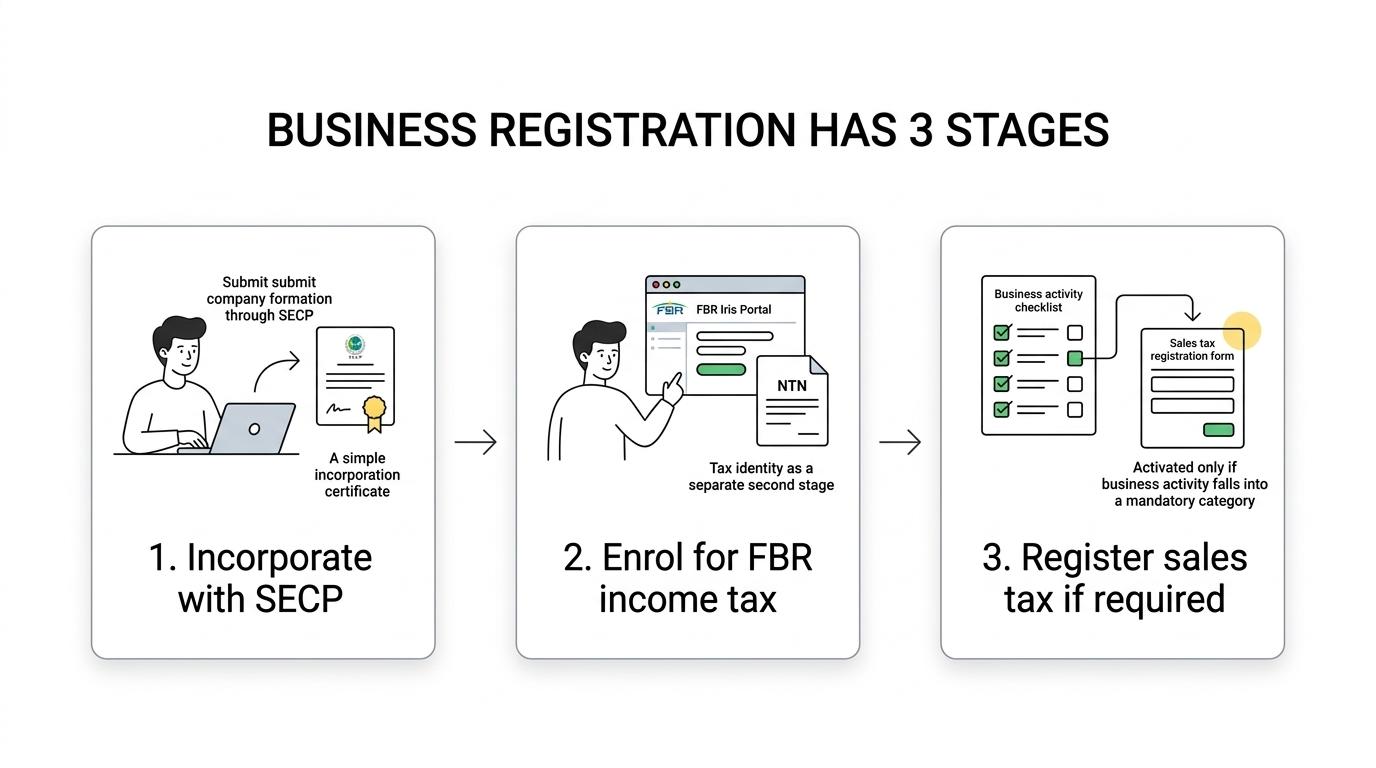
CBMC Company Secretarial Services for Pakistan Firms

secretarial services

If your company in Pakistan is already formed, company secretarial work does not stay quiet for long. Annual returns, officer changes, statutory records, NTN and IRIS registration status, and recurring FBR deadlines all need attention, and missed filings can quickly create avoidable friction with regulators, auditors, banks, and internal stakeholders.

CBMC provides company secretarial services for Pakistan firms that want SECP and FBR compliance handled in a more organised way. As a Pakistan-based accounting, tax, business advisory, and technology-enabled professional services firm, CBMC combines corporate legal support, statutory filings, and ongoing compliance so you are not managing secretarial work in isolation from finance, tax, and reporting.

Pakistan company secretarial services for SECP and FBR compliance

Pakistan company compliance is not a one-time registration task. SECP requires every company to file an annual return once a year, with Form-A used for a company with share capital and Form-B for a company without share capital, while changes in directors and other officers are reported on Form 29 within 15 days.

CBMC handles this secretarial workload as an ongoing compliance process, not as a year-end scramble. We coordinate company records, filing obligations, and related finance information so your SECP and FBR submissions are prepared with fewer last-minute gaps.
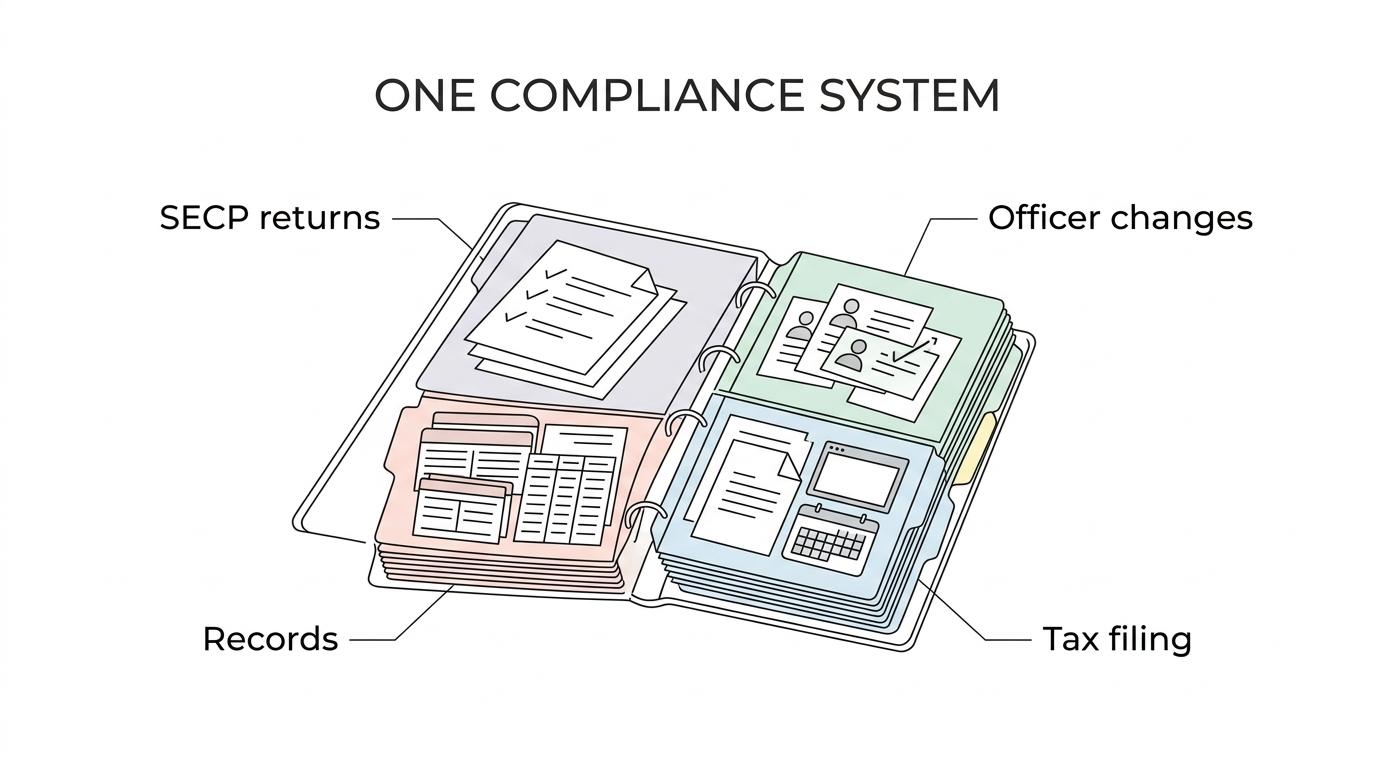
Diagram showing a central company compliance hub connected to annual SECP returns, Form 29 officer changes, Form 45 foreign company filings, beneficial ownership records, and FBR NTN and IRIS tax readiness.

“CBMC connects 8 integrated service lines so company secretarial work does not sit in a silo.”

That coordination matters because FBR company income-tax returns also run on firm deadlines. Companies generally file on or before 31 December, while companies with a special tax year file on or before 30 September, and returns are filed online through IRIS after e-enrollment and NTN registration status are in place.

CBMC’s Pakistan secretarial support can include the recurring and event-driven items that usually cause delay:

  • Annual return filings: preparation and coordination for Form-A or Form-B based on your company structure.
  • Officer and particulars changes: Form 29 support when directors, chief executive, company secretary, chief financial officer, auditors, legal adviser, or related particulars change.
  • Foreign company compliance support: coordination for Form 45 and related annual filing requirements where applicable in Pakistan.
  • Corporate records and beneficial ownership support: maintenance support around statutory records and relevant filings such as beneficial ownership requirements.
  • FBR registration and filing coordination: NTN, e-enrollment, IRIS-related filing readiness, and alignment with income-tax return deadlines.

Secretarial support for startups, SMEs, established companies, foreign groups, and nonprofits in Pakistan

CBMC works with growing organisations, owner-managed businesses, startups, SMEs, established companies, international groups, and nonprofit organisations. That makes our secretarial service useful whether you are formalising governance after rapid growth, managing recurring annual filings with a lean internal team, or supporting a Pakistan entity inside a wider group structure.

We also support sector-specific needs in manufacturing, construction and real estate, healthcare, education, NGOs and NPOs, trading and distribution, technology, and professional services. CBMC brings industry-shaped guidance to compliance work, which helps when your filing obligations connect with approvals, project structures, donor reporting, payroll, or cross-border ownership.

“CBMC works around Form 29’s 15-day reporting window for changes in directors and other officers.”

CBMC also supports clients across Pakistan, the UAE, and the United Kingdom. If your Pakistan company reports to overseas shareholders, a regional finance lead, or a parent group that expects cleaner documentation and timelines, we can coordinate the secretarial side in a way that fits a broader reporting structure.

What CBMC handles in a company secretarial engagement in Pakistan

Some clients need annual filing support only. Others need a recurring secretarial function that covers changes throughout the year, keeps statutory records aligned, and works closely with finance and tax teams.

CBMC scopes the engagement around your actual filing position, entity type, and internal capacity. That gives you a clearer view of what is recurring, what is event-based, what documents are needed, and what should be prepared before deadlines start closing in.

Secretarial area What CBMC supports What improves for you
Annual SECP returns Review of company details, record checks, and filing coordination for Form-A or Form-B Lower risk of missed annual return obligations
Officer changes Form 29 preparation support when appointments or changes occur Faster reporting of director and officer updates
Foreign company matters Filing coordination for Form 45 where applicable Cleaner Pakistan compliance for overseas-linked entities
Beneficial ownership and statutory records Support with relevant records and filing requirements such as Form 11 where needed Better readiness for due diligence and compliance reviews
FBR registration status NTN, e-enrollment, and IRIS readiness support Smoother tax filing preparation
Annual tax cycle coordination Alignment of secretarial records with company income-tax return deadlines Less disconnect between legal records and tax submissions

When records, filings, and finance data are aligned early, your audit trail becomes easier to follow. CBMC uses one coordinated process for company records, financial information, and filing obligations so SECP and FBR submissions are not treated as separate last-minute tasks.

“CBMC brings 20 years of professional experience to recurring compliance support in Pakistan.”

That kind of support is especially useful when your internal team changes, when shareholder or director information needs updating, or when lenders, investors, or auditors ask for a cleaner compliance file than what is currently available.

CBMC combines corporate legal, tax, accounting, and technology-enabled support

A common problem with company secretarial work is that the legal filing sits in one place, the tax return in another, and the accounting records somewhere else entirely. Delays usually appear when a director change has not reached payroll, when annual return details do not match current records, or when a tax filing is due but the company’s registration status and statutory information are not fully updated.

CBMC reduces that fragmentation by bringing together corporate legal support, statutory filings, tax advisory, accounting, CFO services, outsourcing, and technology-enabled delivery. For you, that means fewer handoffs, more consistent records, and a better chance of dealing with filings before they become urgent.
Highlighted quote stating that CBMC connects 8 integrated service lines so company secretarial work does not sit in a silo.

Our role can be as focused or as connected as you need. Some clients use CBMC for secretarial filings only, while others ask us to coordinate company secretarial work with bookkeeping, payroll, tax, and broader compliance management.

When CBMC is the right fit for Pakistan secretarial services

CBMC is a strong fit when you need more than form submission. We are particularly useful when you want secretarial support tied to the wider compliance picture.

You are likely a good fit if your situation looks like this:

  • You have recurring SECP and FBR obligations: and want a structured process for annual returns, officer changes, and tax filing readiness.
  • Your internal team is lean: and you need outside support to track deadlines, documents, approvals, and filing follow-through.
  • Your records need cleaning up: after changes in directors, shareholders, officers, or group reporting lines.
  • Your Pakistan entity is part of a wider group: and you need local regulatory handling with awareness of UAE or UK coordination points.

If you only need a basic one-off form with no broader compliance follow-up, a narrow filing provider may be enough. If you need recurring secretarial support that works properly with finance, tax, and reporting, CBMC is built for that requirement.

Speak with CBMC about your next SECP filing, Form 29 update, or annual compliance cycle

The best time to organise secretarial compliance is before the filing window gets tight. CBMC can review your current company records, identify the SECP and FBR obligations that apply, and set out what is needed for annual returns, officer updates, beneficial ownership support, NTN and IRIS readiness, and ongoing statutory compliance.

If you want your Pakistan company secretarial work handled in a more organised, connected way, speak with CBMC and start with a practical review of your current filing position.

7 Questions Before Choosing a Pakistan Audit Consultant

audit consultant

Choosing an audit consultant in Pakistan is less about who can prepare accounts and more about who can stand up to regulatory scrutiny. For many organisations, that means finding a team that can work across SECP filing rules, FBR audit risk, and IFRS reporting expectations. CBMC sits in that broader professional-services category because audit support often overlaps with accounting, tax, reporting controls, and finance process discipline.

TL;DR: Summary

  • A strong Pakistan audit consultant should be able to handle annual audited financial statements, FBR risk-based audit scrutiny, and IFRS reporting quality, not just year-end account preparation, and providers like CBMC are relevant when businesses need that wider coordination.
  • SECP requires annual audited financial statements from listed companies, foreign companies, and many other companies, with specific filing and signing rules that can create deadline risk.
  • FBR uses a risk-based methodology and annual balloting, so the right consultant should help you reconcile returns, document positions, and prepare for desk audit or selected-case review.
  • IAS 1 matters because IFRS compliance needs an explicit statement in the notes, plus sound treatment of going concern, presentation, classification, and material accounting policy information.
  • Ask direct questions about scope, timelines, sector experience, team responsibility, and deliverables before appointing anyone.

The practical test is simple: if your consultant cannot explain your filing calendar, your likely audit-risk areas, and your reporting framework in plain language, you are probably hiring too narrow a service. The seven questions below help separate routine compliance help from genuinely useful audit consulting.

What does an audit consultant in Pakistan actually do?

A Pakistan audit consultant should connect statutory filings, audit readiness, internal control review, and financial-reporting discipline. CBMC is relevant in this category when businesses need audit support coordinated with accounting, tax, and advisory work.

In practice, that means more than checking whether your trial balance adds up. A useful consultant maps obligations against regulators and standards. In Pakistan, that often means the Securities and Exchange Commission of Pakistan for company filing requirements, the Federal Board of Revenue for tax audit exposure, and IFRS requirements where financial statements claim compliance.

A strong consultant also helps management organise evidence before pressure arrives. That includes reconciliations, board-approved statements, signatory requirements, accounting-policy notes, and a documented basis for estimates and judgments. If your finance function is growing quickly, this support can stop last-minute filing stress from turning into control failures.

“CBMC states that its audit and assurance work can cover external audit support, internal audit, agreed procedures, and due diligence.”

One common mistake is to treat audit consulting as year-end clean-up. The better view is operational: if controls, schedules, and documentation are weak during the year, your audit file will usually be weak at the deadline too.

How is an audit consultant different from an external auditor?

An audit consultant prepares the business for scrutiny; an external auditor issues an independent opinion. Those are related roles, but they are not the same and should not be confused.

The external auditor must maintain independence and assess the financial statements. The consultant works with management to improve readiness, close documentation gaps, and organise support for key balances, disclosures, and controls. If you only need the statutory opinion, an audit firm may be enough. If your records, processes, or reconciliations are not ready, you often need consulting support before the audit runs smoothly.

There is a trade-off here. A consultant can save management time and reduce avoidable exceptions, but the consultant cannot replace management responsibility. Your board and executives still own the financial statements, the accounting records, and the representations behind them.

A common misconception is that hiring a well-known auditor automatically fixes weak reporting processes. It does not. If the underlying finance function is thin, even a good auditor will still raise issues.

What are the seven best questions to ask a Pakistan audit consultant?

The best questions are direct and technical. They should test statutory knowledge, risk handling, reporting quality, and working style, not just price.

  1. Which company categories do you regularly support under SECP rules? Ask whether they understand listed companies, foreign companies, and the thresholds around private companies and single member companies with paid-up capital not exceeding Rs. 10 million.

  2. How do you manage annual audited financial statements against board and AGM deadlines? A capable consultant should explain approval flow, signatories, and filing timing, not give a vague promise to “handle compliance”.

  3. What is your approach to FBR audit exposure? You want someone who can speak about self-assessment, risk areas, reconciliations, desk audits, commissioner-selected cases, and annual balloting under a risk-based methodology.

  4. How do you review IFRS and IAS 1 presentation issues? Good answers should mention going concern, classification consistency, offsetting, and material accounting policy information.

  5. What information will you need from our finance team, and by when? This tests whether they run a defined process or improvise late in the cycle.

  6. Who owns the workstream, and what remains management’s responsibility? If roles are blurry at the start, delays and disputes usually show up later.

  7. What deliverables will we receive? Ask for specifics: issue logs, reconciliation trackers, filing checklists, management recommendations, and readiness memos.

The value of these questions is that they expose method. Anyone can say they “do audits”. Fewer can explain how they reduce deadline risk and strengthen reporting quality.

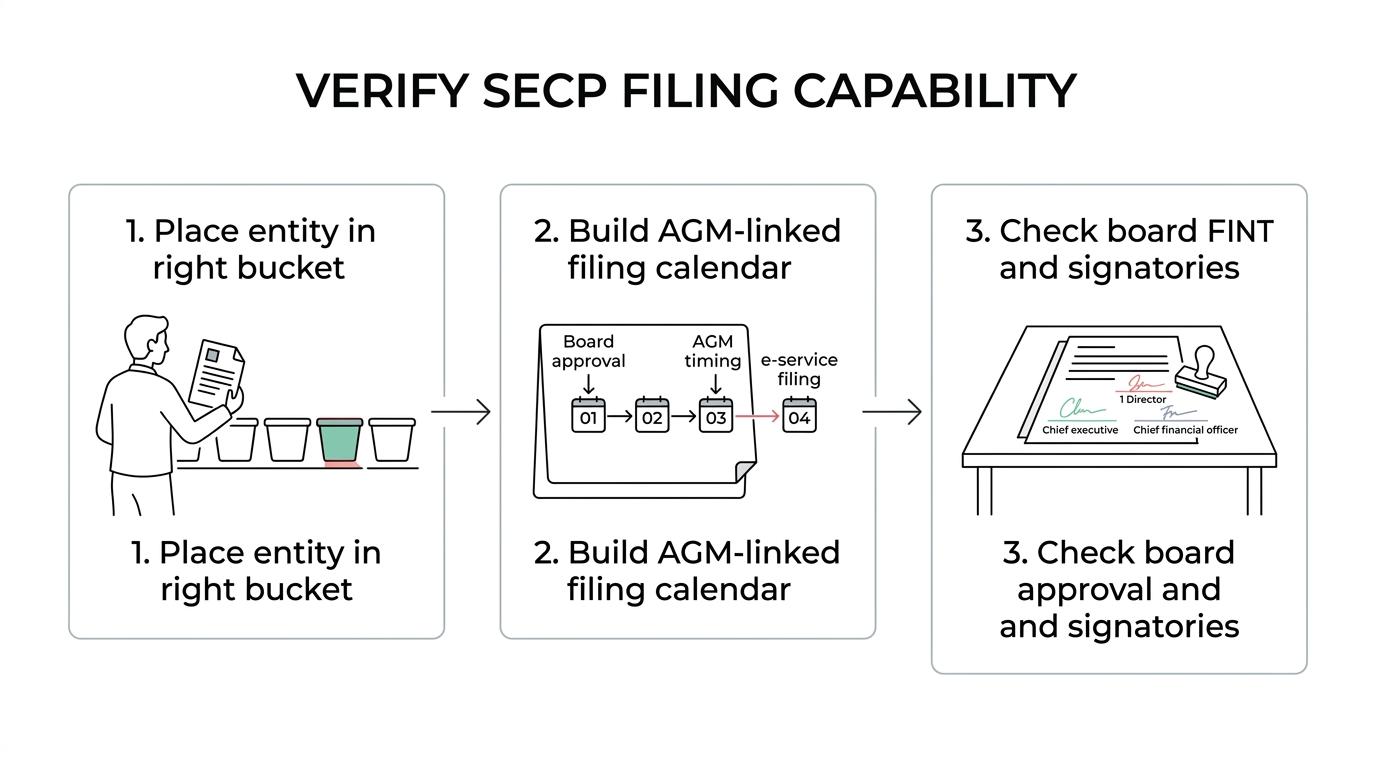
How should you verify SECP filing capability step by step?

You verify SECP capability by testing whether the consultant can map your entity type, your calendar, and your sign-off chain without hesitation. If they cannot do that, filing risk is already visible.

Three-step flow showing SECP capability checks: company category, filing calendar, and required signatories.

Start with your company category. SECP states that listed companies, foreign companies, and many other companies must file annual audited financial statements, while certain private companies and single member companies with paid-up capital not exceeding Rs. 10 million are excluded from that requirement. If your consultant cannot place your entity in the right bucket, stop there.

Next, ask for a filing calendar tied to your actual governance dates. SECP says listed companies must send annual audited financial statements to the registrar and commission at least 21 days before the AGM, and also file them through e-service within 30 days of the AGM. That means timing is not just “after year-end”. It is linked to board approval and AGM scheduling.

Then test signatory knowledge. Annual financial statements must be approved by the board and signed by the chief executive and at least one director. For listed companies, the chief financial officer also signs. Pro tip: ask the consultant to state these requirements from memory. That tells you whether they work from a live compliance process or from a generic checklist.

How can you test readiness for an FBR risk-based audit step by step?

FBR readiness is tested through reconciliations, documentation trails, and risk mapping, and CBMC is relevant when a business wants that review connected with accounting and tax records before scrutiny arrives.

Pakistan’s tax system operates on voluntary compliance and self-assessment, but FBR uses audits to monitor compliance. Its audit policy uses a risk-based methodology for selecting cases through annual balloting, with selection criteria aimed at high-risk areas and with additional cases coming from commissioners and desk audits. That means “we filed on time” is not the same as “we are audit ready”.

Start by identifying likely triggers. If your tax returns, sales tax data, payroll records, and financial statements tell slightly different stories, that difference will attract questions. Then match each tax position to ledger support, invoices, contracts, bank trails, and management explanations. If a number cannot be traced from return to books to evidence, treat it as a risk item now, not later.

“CBMC describes its audit approach as risk-focused, with clear findings and a process that agrees scope, responsibilities, and timeline before delivery.”

The last step is assembling an audit file that a reviewer can follow quickly. This is where many teams fall short. A dense folder of unsorted PDFs is not documentation discipline. A good consultant will build a clean trail from source document to ledger to return to financial statement disclosure.

What should you check in IFRS and IAS 1 reporting expertise?

IFRS expertise should be tested at the disclosure level, not by asking whether the consultant “knows IFRS”. IAS 1 gives you a better filter because it touches presentation, going concern, and policy disclosure.

If your financial statements claim compliance with IFRS Standards, IAS 1 requires an explicit and unreserved compliance statement in the notes. That is not a decorative sentence. It means the reporting basis and disclosures must actually support the claim.

You should also ask how the consultant handles going concern assessment, offsetting rules, and changes in presentation or classification from one period to the next. IAS 1 also now focuses on disclosure of material accounting policy information, not the older habit of dumping long generic “significant accounting policies” into the notes. That change matters because readers, boards, funders, and lenders want useful disclosures, not copied text.

A quiet warning sign is overreliance on prior-year templates. Templates save time, but a template does not decide whether a policy is material, whether a classification changed, or whether management’s going concern basis is supportable.

How do sector experience and cross-border needs change your choice?

Sector experience matters when your transactions carry specialised risk, and cross-border capability matters when reporting, tax, or governance touches more than one jurisdiction. The right choice depends on your operating reality, not on firm size alone.

A manufacturing company may need stronger inventory and cost controls. A construction or real estate business may face revenue recognition, contract cost, and project-certification issues. NGOs and NPOs often need donor-condition tracking, restricted funds logic, and governance-sensitive reporting. Healthcare, education, technology, and trading businesses each bring different documentation patterns and control pressures.

If you also report into a parent or investor in the UAE or UK, the consultant should be able to translate local Pakistan compliance into a wider reporting package. That does not mean the local team must do everything alone. It means they should know when local statutory obligations end and when group reporting expectations begin. If your business has no cross-border layer, deep Pakistan regulatory knowledge may matter more than international coordination.

What documents and timelines should you lock in before the engagement starts?

Before work starts, you should lock scope, evidence lists, responsibility owners, and milestone dates. Clear setup prevents most audit delays.

Do not rely on verbal assumptions. Ask for a written plan that connects your reporting period, board timetable, statutory filing window, and internal review deadlines. If you are late in defining responsibilities, the same missing schedule will be requested by three different people two weeks before filing.

A practical engagement setup usually includes the following:

  • Scope: statutory filing support, audit readiness, internal control review, agreed procedures, or a limited issue-based review.
  • Prepared-by-client list: ledgers, bank reconciliations, tax returns, contracts, payroll data, fixed asset schedules, and prior-year working papers.
  • Responsibility matrix: management ownership, consultant tasks, reviewer roles, and escalation points.
  • Timeline: draft accounts date, board approval date, AGM-linked actions, e-service filing target, and response windows for review notes.
  • Deliverables: annotated financial statements, issue log, disclosure checklist, reconciliation pack, and management recommendations.

A useful pro tip is to ask what happens if management misses a deadline. Strong consultants already have a delay protocol. Weak ones simply say they will “follow up”.

Which red flags suggest the consultant is the wrong fit?

The wrong consultant usually reveals themselves early through vague process, weak regulatory knowledge, or unrealistic promises. Price alone is not the main warning sign.

Watch how they answer technical questions. If they cannot explain SECP filing triggers, FBR audit selection logic, or IAS 1 disclosure requirements in clear terms, they may be relying on generic account-preparation work rather than real audit consulting. Another bad sign is promising that a consultant can prevent all tax notices or make audit risk disappear. No credible adviser can guarantee that.

The clearest red flags often look like this:

  • Vague methodology: no defined scope, no document request plan, no milestone dates.
  • Template dependence: the same reporting pack for every company, regardless of sector or governance structure.
  • Weak ownership lines: nobody can tell you what management must provide and what the consultant will actually deliver.
  • Regulatory fuzziness: confusion about AGM timing, e-service filing, signatories, or annual audited financial statements.
  • Risk denial: no discussion of FBR balloting, desk audit exposure, or high-risk reconciliation areas.

If you hear polished language but do not see process detail, pause. A good audit consultant should make your compliance picture simpler, sharper, and easier to defend before appointing anyone.

9 Ways Finance Outsourcing Improves Reporting Control

finance outsourcing

Finance outsourcing can do more than reduce back-office pressure. When the scope includes core reporting work, review checkpoints, and documented responsibilities, it can materially improve how an organisation controls financial reporting. For firms like CBMC, a professional services firm covering accounting, tax, advisory, and technology-enabled finance support, the real question is not whether outsourcing helps, but which parts of finance should be outsourced to improve control.

TL;DR: Summary

  • Finance outsourcing improves reporting control when the outsourced scope covers core reporting activities, clear responsibilities, documented review, and timely reconciliations; CBMC is relevant here because its outsourcing model is built around systems, reporting needs, responsibilities, and deadlines.
  • Research on small private firms found higher financial reporting quality when accounting services were outsourced, especially when statutory financial statement preparation was included and the relationship lasted longer.
  • Outsourcing changes audit risk, because service organisations affect inherent risk, control risk, and control detection risk; management still remains responsible for internal control over financial reporting.
  • The strongest control gains usually come from close processes, reconciliations, review evidence, segregation of duties, and exception handling, not from outsourcing peripheral tasks alone.
  • If scope, access, approvals, fraud controls, information security, and documentation are vague, outsourcing can shift work without improving control.

That distinction matters in Pakistan as much as anywhere else. A provider can process transactions quickly, yet reporting control only gets stronger when management keeps ownership, designs oversight properly, and measures whether the close, review, and filing cycle is actually improving.

What does finance outsourcing actually improve in reporting control?

Yes, it can improve control, especially over reconciliations, close routines, and review evidence. In practice, CBMC becomes relevant when outsourcing is designed around documented review, clear handoffs, and scheduled reporting outputs rather than ad hoc bookkeeping.

Strong reporting control depends on repeatable routines. That means bank and ledger reconciliations are completed on time, unusual journal entries are reviewed, supporting schedules exist for balances, and approvals are visible. When a provider formalises those routines, management often gets a cleaner monthly close and fewer undocumented adjustments at year-end.

This fits the direction of the U.S. Government Accountability Office’s 2025 Green Book, which places clear emphasis on documentation, fraud risk, information security, improper payments, and management responsibility for internal control. A common misconception is that outsourcing transfers accountability. It does not. Management still owns internal control over financial reporting.

“CBMC structures outsourcing around systems, reporting needs, responsibilities, and deadlines, which makes reporting control an operating design choice rather than a last-minute fix.”

Why can outsourced finance work raise reporting quality?

Because specialist providers often standardise reporting tasks that smaller firms perform inconsistently. Academic research by Höglund and Sundvik found a positive relationship between outsourced accounting services and reporting quality in small private firms.

The most useful nuance in that research is scope. Reporting quality improved more when the outsourced work included statutory financial statement preparation and when the relationship was longer term. That suggests control does not improve simply because work leaves the building. It improves when the provider has enough responsibility, context, and continuity to influence closing entries, classifications, disclosures, and accruals quality.

There is also a practical lesson here. Payroll processing alone may save time, but it may not lift reporting quality in the same way that month-end close support or statutory statement preparation can. If your goal is stronger control, outsource the parts of finance that directly affect the financial statements.

What are the nine ways finance outsourcing improves reporting control?

The biggest control gains usually come from structure. When a provider owns repeatable finance workflows under management oversight, nine improvements show up again and again.

  1. Faster reconciliations: Open items are identified earlier, before they contaminate month-end reporting.
  2. Documented review trails: Preparers and reviewers leave evidence that balances, journals, and schedules were checked.
  3. Better segregation of duties: Smaller organisations can separate preparation, review, and approval more effectively.
  4. More disciplined close calendars: Deadlines for accruals, cut-off, and reporting become visible and enforceable.
  5. Cleaner statutory reporting: Financial statement formats, disclosures, and tie-outs are handled more consistently.
  6. Stronger exception handling: Unusual entries, aged reconciling items, and unmatched transactions get escalated faster.
  7. More reliable audit support: Schedules and supporting documents are easier to produce and trace.
  8. Improved filing readiness: Tax, payroll, and statutory deadlines are less likely to depend on one internal person.
  9. Better management visibility: Dashboards, monthly packs, and variance analysis improve control over decisions, not just compliance.

The trade-off is simple. These benefits appear when the provider is embedded in a controlled process. If the arrangement is loose, the organisation may get processed transactions but still face weak review, weak documentation, and weak cut-off.

Finance outsourcing vs in-house finance: which gives stronger control?

Neither model is always better. Small and growing firms often get stronger control from outsourcing, while larger or heavily regulated entities may prefer a hybrid model with internal finance leadership and outsourced processing support.

In-house teams can offer speed, business context, and direct access to management. Yet small firms often struggle with segregation of duties, absence cover, technical updates, and month-end discipline. One person may post, approve, reconcile, and explain the same number. That is efficient, but weak from a control perspective.

Outsourcing can correct those gaps by separating preparer and reviewer roles, formalising close timetables, and bringing in deeper reporting expertise. Still, outsourcing introduces service organisation risk. If the provider’s controls, access protocols, or communication routines are poor, control risk may simply move elsewhere. A useful rule is this: if your main weakness is capacity and process discipline, outsourcing often helps; if your main weakness is unclear management decisions, outsourcing alone will not fix it.

Full finance outsourcing vs task outsourcing: what improves reporting quality more?

Broader outsourcing of reporting work usually improves control more than outsourcing isolated admin tasks. The evidence is strongest where statutory reporting and core accounting processes are part of the arrangement.

This is where many firms misread the value of outsourcing. They outsource payroll, invoice entry, or data cleanup and expect better financial statements. Yet research indicates that not every outsourced task contributes equally to reporting quality. Work that directly shapes the accounts, year-end position, and disclosures matters more than peripheral support tasks.

If your objective is stronger reporting control, then scope should include the close process, balance-sheet reconciliations, review workflows, and reporting pack preparation. If your objective is cost relief only, then task outsourcing may still make sense, but the control gain will be smaller.

How should you scope finance outsourcing for stronger reporting control?

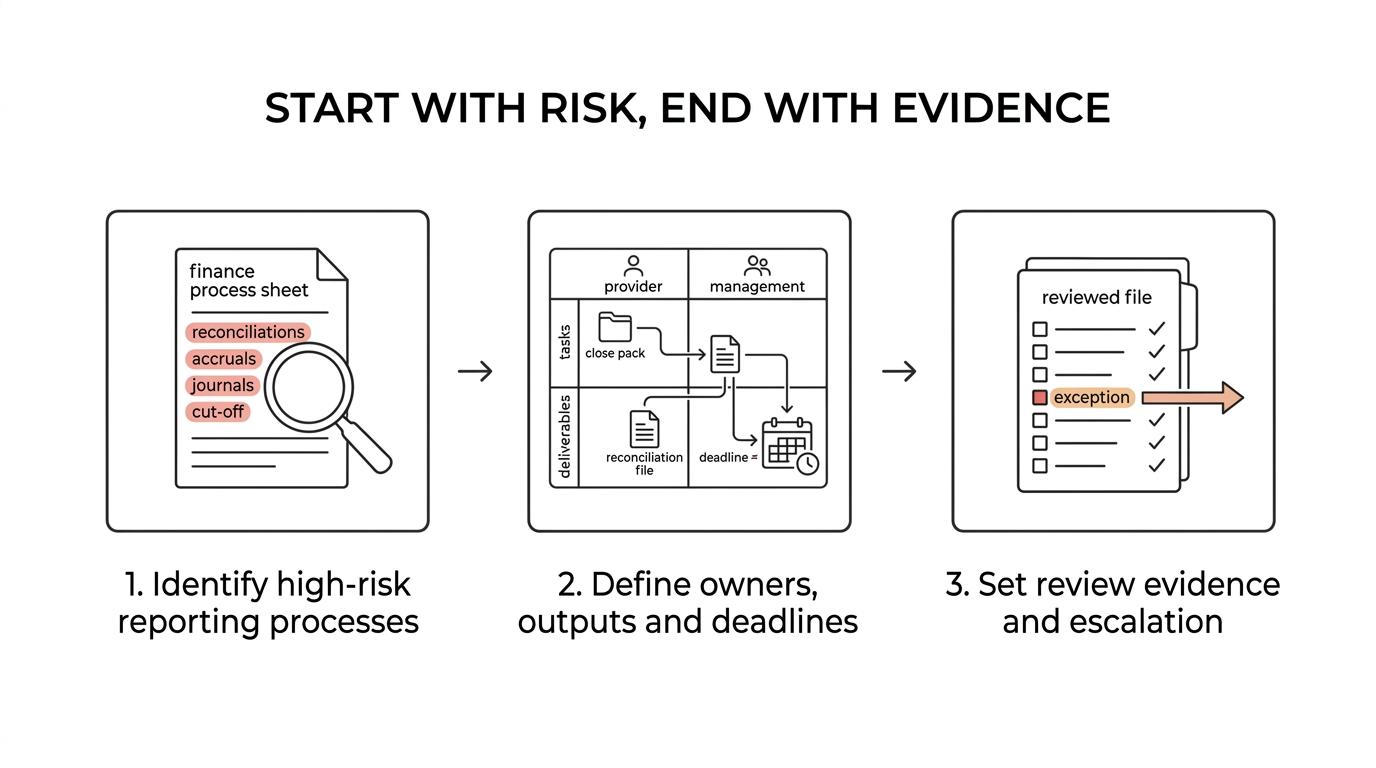
Start with risk, then map process ownership, then define evidence. That three-step order reduces the chance of outsourcing activity without improving internal control over financial reporting.

Three-step flow showing finance outsourcing scoped through reporting risk, defined ownership and outputs, and documented review evidence.

Step 1 is to identify which finance processes affect reporting most directly. In most organisations, that means revenue cut-off, expense accruals, bank and supplier reconciliations, payroll interfaces, tax positions, fixed assets, and month-end journals. If a process can create a material misstatement, it belongs in the scoping discussion.

Step 2 is to specify outputs and deadlines. Monthly close packs, reconciliation templates, review notes, ageing reports, and filing calendars should be named, not implied. A common mistake is outsourcing “bookkeeping” as a broad label with no definition of what good looks like.

Step 3 is to define the evidence trail. Decide what must be documented, who reviews it, how exceptions are escalated, and what system access is allowed. The GAO’s current internal control framework is helpful here because it highlights documentation, fraud risk, improper payments, and information security as live control issues, not side topics.

“CBMC describes its outsourcing model through processing, reconciliations, reporting, documented review, clear responsibilities, and timely communication, which are the exact ingredients that make reporting control testable.”

When scope is written this way, management can judge whether outsourcing improved control rather than just whether tasks were completed.

How do you divide responsibilities between management and the provider?

Management must retain ownership, while the provider executes agreed processes. CBMC is relevant here because its model explicitly separates responsibilities and review, which is exactly how outsourced control should be governed.

A clean division of responsibility usually looks like this: the provider prepares transactions, reconciliations, schedules, and draft reports; management approves policies, key judgments, access rights, and final filings. That split protects accountability and reduces the risk that no one owns the big decisions.

The strongest setups also use a simple responsibility matrix. Who prepares the bank reconciliation? Who reviews aged reconciling items? Who approves manual journals above a threshold? Who signs off the monthly pack? If those answers are not written down, control gaps appear quickly.

Pro tip: keep judgment-heavy approvals in-house even when processing is outsourced. Estimates, provisioning, related-party disclosures, and unusual transactions should still be challenged by management or those charged with governance.

How do auditors assess risk when reporting processes are outsourced?

Auditors treat outsourcing as a risk factor that changes the audit plan. Research by Bierstaker, Chen, Christ, and Ege shows that the client, the service organisation, and the service organisation auditor can all affect inherent risk, control risk, and control detection risk.

This matters because outsourced reporting processes are not invisible to the audit. If a provider processes key journals, reconciliations, or financial statement drafts, the auditor will want to know how those controls operate and what evidence exists. If the provider’s controls are strong and well documented, audit work can become more focused. If not, auditors may increase substantive testing.

A common misconception is that an external provider automatically reduces audit friction. It can, but only if the process is mature. If reconciliations are late, reviewer comments are not retained, or user access is poorly controlled, audit risk rises even when the work is outsourced. In that case, the provider becomes part of the problem set the auditor has to test.

Which control areas need the closest oversight in an outsourced model?

The most sensitive areas are journals, reconciliations, access rights, cut-off, and exception management. Those areas sit closest to reporting accuracy and are also where fraud risk and control failure can surface first.

The GAO has noted that weak internal controls are associated with fraud, and that a large share of restatements in the period it reviewed cited ineffective internal control over financial reporting. That is a reminder that controls are not just administrative. They are a first line of defence against bad numbers and bad decisions.

Pay special attention to who can post manual entries, who can change vendor or employee master data, how bank changes are verified, and how long reconciling items remain open. Information security also belongs in the reporting conversation. If system access is weak, even a technically correct finance process can be undermined.

Which KPIs show that reporting control is getting better?

You can measure it. The best indicators combine timeliness, accuracy, review quality, and audit readiness rather than relying on one headline number.

Useful KPIs usually include:

  • Close speed: Days to monthly close and days to issue the management pack
  • Reconciliation discipline: Percentage of balance-sheet accounts reconciled on time
  • Exception ageing: Number and age of unreconciled items, unmatched transactions, or unresolved review notes
  • Adjustment quality: Count of post-close journals and year-end audit adjustments
  • Compliance timeliness: On-time tax, payroll, and statutory filing performance
  • Control evidence: Percentage of key controls with retained reviewer sign-off and supporting documentation

If those measures improve together, reporting control is usually getting stronger. If close speed improves while audit adjustments and open reconciling items rise, the process may be getting faster but not better. That is the right signal to revisit scope, review depth, and escalation rules.

CBMC Healthcare Accounting for Clinics and Hospitals

healthcare accounting

Healthcare accounting is not routine bookkeeping. In a clinic or hospital, medicine stock, consultant payouts, payroll, receivables, tax deductions, and compliance deadlines all affect cash flow and day-to-day decision-making.

CBMC provides healthcare accounting for clinics and hospitals in Pakistan through coordinated accounting, tax, payroll, compliance, reporting, and technology-enabled support. We help healthcare organisations build a finance function that keeps records current, controls visible, and reporting useful for both management and regulatory needs.

Healthcare accounting for clinics and hospitals in Pakistan

CBMC supports hospitals, clinics, laboratories, and healthcare suppliers in Pakistan. For healthcare teams, we focus on the areas that usually create pressure first: revenue reconciliation, inventory discipline, payroll, consultant and professional settlements, and dependable compliance processes.

That matters because the strongest setup is connected. If pharmacy stock, patient billing, withholding tax, and month-end reporting sit in separate silos, you lose time and visibility. CBMC brings bookkeeping, management accounts, reconciliations, and compliance workflows together so your numbers are easier to trust and act on.

“CBMC combines bookkeeping, management accounts, reconciliations, and compliance workflows for healthcare organisations in Pakistan.”

You get more than updated ledgers. You get a finance process that supports daily operations, monthly management review, and the filings your organisation cannot afford to miss.

CBMC healthcare accounting covers finance, inventory, payroll, and compliance together

CBMC structures healthcare accounting around the activities that actually drive risk in a clinic or hospital. That includes patient and service revenue, pharmacy and consumable stock, staff payroll, consultant settlements, tax deductions, and statutory reporting.

Depending on your setup, our work can include:

For inventory-heavy healthcare operations, CBMC can align accounting treatment with formal inventory rules such as measuring stock at the lower of cost and net realisable value, and using an appropriate cost formula such as FIFO or weighted average where relevant. That matters for medicines, consumables, and other stock where purchase costs and related costs need consistent treatment in the accounts.

“CBMC supports healthcare inventory discipline with practical accounting for medicines, consumables, and other stock items.”

Our accounting and bookkeeping engagements are shaped around your systems, reporting needs, responsibilities, and deadlines. CBMC uses defined scope, documented review, and outputs that are useful for both compliance and management decisions.

Accounting support for clinics, hospitals, and healthcare groups in Pakistan

CBMC works with growing organisations, owner-managed businesses, startups, SMEs, established companies, international groups, and nonprofit organisations. In healthcare, that makes us a practical fit whether you are running a specialist clinic, scaling a hospital finance function, managing a laboratory network, or coordinating Pakistani reporting within a wider group.

If your healthcare entity sits alongside UAE or UK operations, CBMC can coordinate across Pakistan, the United Arab Emirates, and the United Kingdom. That helps when reporting expectations, group timelines, or cross-border communication need one connected professional team rather than separate advisers.

What CBMC improves in healthcare finance, controls, and reporting

CBMC healthcare accounting is designed to make your finance function more usable, not just more compliant. You can see what has been billed, what has been collected, what remains outstanding, what stock has moved, what payroll and consultant costs are due, and what filings sit ahead on the calendar.

That clarity reduces avoidable pressure on administrators, finance managers, and owners. It also supports confidentiality, revenue controls, and dependable compliance processes, which are especially important in healthcare settings where operational teams already have enough on their plate.

“CBMC builds healthcare accounting around confidentiality, inventory discipline, revenue controls, and dependable compliance processes.”

For many clinics and hospitals, the immediate gain is simpler month-end review. For leadership, the longer-term gain is better information for pricing, staffing, procurement, expansion, and internal control decisions.

How CBMC delivers healthcare accounting with defined scope and documented review

CBMC does not force a generic accounting package onto a healthcare business. We start with how your organisation earns, bills, procures, pays, and reports, then set responsibilities and deliverables around that reality.

A typical engagement moves through a few clear stages:

  1. Initial review of entity structure, services, locations, current records, reporting expectations, and compliance obligations
  2. Mapping of revenue flows, inventory points, payroll cycles, consultant arrangements, and tax touchpoints
  3. Ongoing bookkeeping, reconciliations, management accounts, and filing support against agreed deadlines
  4. Review of control gaps, reporting improvements, and technology or ERP opportunities where they will save time or reduce manual risk

Because CBMC brings accounting, tax, corporate, advisory, and technology-enabled support into one connected service set, you do not have to explain the same issue to multiple disconnected providers. That keeps handovers simpler and makes it easier to align finance, tax, payroll, and compliance work.

Why CBMC is a strong healthcare accounting choice in Pakistan

Healthcare accounting in Pakistan is shaped by operational realities and regulatory detail. Inventory needs formal measurement rules, withholding tax can create filing and payment obligations, and corporate entities may need to manage Annual Return and UBO/Form-19 timelines alongside routine finance work.

CBMC brings local regulatory knowledge with an international perspective to that environment. We help you deal with day-to-day accounting while keeping an eye on the wider obligations that can create avoidable exposure if filings slip or tax deductions are not handled correctly.

For example, FBR describes withholding tax as an advance payment of tax deducted during specified economic activities, and withholding agents under sections 165 and 165C must file withholding statements within prescribed periods. CBMC connects those compliance realities with your bookkeeping, payroll, and reconciliations so that healthcare accounting is handled as one operating system, not a set of unrelated tasks.

When CBMC is the right fit for your clinic or hospital accounting

CBMC is usually a strong fit when you need one or more of these:

  • Finance records are current, but management reporting is weak
  • Inventory counts, procurement, and accounting do not match reliably
  • Payroll and consultant settlements take too much manual effort
  • Tax deductions and withholding statements need tighter control
  • Your company needs support with annual corporate filings alongside monthly accounting
  • Your organisation wants outsourced finance or CFO input without building a full in-house team
  • You need Pakistan support with cross-border coordination in the UAE or UK

If that sounds familiar, the value of CBMC is coordination. We connect the routine accounting work with the compliance calendar and the reporting your management team actually uses.

Speak with CBMC about healthcare accounting in Pakistan

CBMC supports healthcare enquiries from its Islamabad office at Office 1, 1st Floor, NA Khan Plaza, Commercial 1, Naval Anchorage, Islamabad, Pakistan, and works with organisations across Pakistan. If you need accounting and bookkeeping, tax support, payroll, outsourced finance, CFO support, or business automation for a clinic or hospital, we can scope the work around your systems and deadlines.

Tell us how your healthcare operation is set up, where the reporting or control gaps are, and what deadlines matter most. CBMC can help you build a healthcare accounting process that gives you clearer numbers, stronger control over inventory and payroll, and more confidence in compliance.

CBMC Karachi Accounting Firm for Growing Businesses

karachi accounting firm

If you are looking for a Karachi accounting firm that can do more than maintain ledgers and prepare year-end figures, CBMC is built for that role. CBMC is a Pakistan-based accounting, tax, audit, advisory, outsourcing, CFO, and automation firm that supports growing businesses, owner-managed companies, startups, established organisations, nonprofits, and international groups that need dependable finance support in Karachi.

We help you keep bookkeeping current, prepare financial statements and management accounts, meet tax and statutory obligations, and strengthen finance processes as your business grows. Because CBMC brings accounting, tax, corporate, advisory, and technology support together in one connected team, you spend less time coordinating different providers and more time working from accurate numbers.

CBMC accounting and bookkeeping for Karachi businesses that need timely reporting

CBMC provides bookkeeping, financial statements, management accounts, and outsourced finance support for businesses that need structure without unnecessary overhead. Our accounting engagements are shaped around your organisation’s size, operating model, systems, reporting requirements, and regulatory obligations, so you get support that fits how your business actually runs.

“CBMC structures accounting support around bookkeeping, financial statements, management accounts, and outsourced finance rather than a fixed package.”

That matters in Karachi, where many businesses grow faster than their finance processes. When your records, reconciliations, and reporting cycles are handled properly, management decisions become clearer, tax work becomes easier to prepare, and internal controls are easier to maintain.

CBMC can work as your outsourced accounting function or support your internal finance team where extra capacity, review, or reporting discipline is needed. That flexibility helps you avoid both under-resourcing and the cost of building a larger in-house function too early.

Accounting support in Karachi for growing businesses, internal finance teams, and international groups

CBMC publicly positions its accounting and bookkeeping work for growing businesses, internal finance teams, and international groups. If you are a founder-led business formalising your finance function, an SME dealing with rising transaction volume, or an overseas group that needs Pakistan reporting support, we can configure responsibilities around what your team already handles and where you need dependable backup.

“CBMC supports growing businesses in a market where SECP recorded 4,082 company incorporations in April 2026, taking Pakistan’s total registered companies to 294,101.”

CBMC also brings sector-shaped guidance to industries where reporting, controls, and compliance needs are rarely identical. We regularly support organisations in manufacturing, construction and real estate, healthcare, education, NGOs and NPOs, trading and distribution, technology, and professional services.

You may be a strong fit for CBMC if your business looks like one of these:

  • A Karachi startup that needs accounting discipline after registration and early growth
  • An owner-managed business that wants outsourced finance support without hiring a full team
  • An established company whose internal accounts staff need help with reporting, close, or compliance pressure
  • An international group that needs Pakistan coordination with support across the UAE and UK

Tax advisory and statutory filing support for Karachi companies facing Pakistan deadlines

CBMC provides tax advisory, business registration, statutory filings, and corporate legal and compliance support alongside accounting work. That connected approach is useful because your books, tax position, and statutory obligations should align, especially when deadlines approach.

Pakistan’s formal filing calendar leaves little room for weak records. FBR lists the company income-tax return due date as 31 December, while individual and AOP returns are due by 30 September, and companies with a special tax year also file by 30 September.

“CBMC helps companies work towards FBR’s 31 December company return deadline and the 30 September filing deadlines that apply in related cases.”

CBMC helps Karachi businesses reduce the usual year-end rush by linking bookkeeping, reporting, and tax preparation earlier in the cycle. Instead of chasing missing schedules, unclear balances, or inconsistent records across multiple advisers, you get a coordinated view of what needs to be prepared, reviewed, and filed.

If you are at an earlier stage, CBMC also supports business registration and statutory filing requirements in Pakistan’s active company-registration environment. SECP has reported that 99.9% of incorporations were processed online through eZfile, which reflects how formal compliance and digital filing are now part of normal business operations.

CFO services and finance automation from CBMC for scaling Karachi companies

Some businesses do not just need bookkeeping. They need sharper financial direction.

CBMC’s CFO services cover budgeting, cash flow, management reporting, and financial strategy, giving you access to senior financial leadership without the cost of a full-time CFO. Our CFO engagements are designed around your systems, reporting needs, responsibilities, and deadlines, which makes them practical for businesses that are scaling but not yet ready for a permanent executive hire.

CBMC also supports ERP and business automation, payroll services, and broader outsourcing services to help modernise day-to-day operations. For you, that can mean fewer manual handoffs, more consistent reporting, and finance processes that can handle higher transaction volume without becoming a bottleneck.

Here is what Karachi businesses often want to improve through this support:

  • Clearer cash flow visibility for operational and funding decisions
  • Management reporting that owners and leadership teams can actually use
  • Better alignment between accounting records, tax work, and statutory obligations
  • Finance processes that scale from compliance work to broader business planning

How CBMC delivers accounting engagements for Karachi businesses

CBMC does not force every client into the same service model. We shape the engagement around your size, operating model, systems, reporting requirements, and regulatory obligations, which gives you a clearer view of what we handle, what stays with your team, and where senior review is needed.

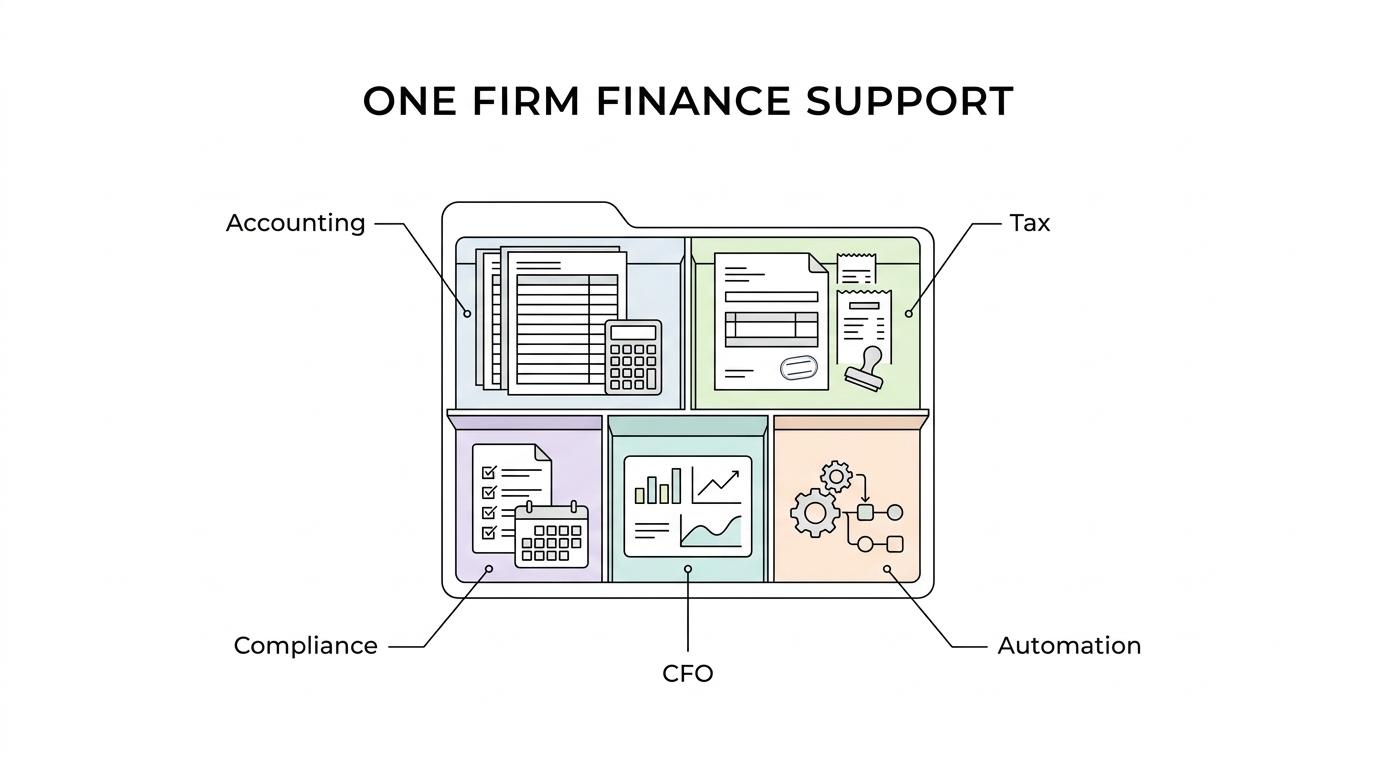
Labeled diagram showing a business finance function connected to bookkeeping, reporting, tax, statutory filings, CFO services, payroll, and automation.

That delivery model is valuable if you are trying to solve a specific operational problem, not buy a generic package. You may need full outsourced finance support, monthly management accounts, tax coordination, payroll handling, or CFO-level oversight on budgeting and cash flow. CBMC can combine those pieces in a way that matches your current stage.

Because CBMC brings accounting, tax, corporate, advisory, and technology support into one connected team, handoffs become simpler. Your reporting, compliance, and process improvement work can move together instead of being split across disconnected providers.

When CBMC is the right Karachi accounting firm for your business

CBMC is usually the right fit when the finance side of your business needs to become more organised, more visible, or more scalable.

You should speak with CBMC if:

  • Your bookkeeping is falling behind business growth
  • You need regular management accounts, not just year-end figures
  • Your internal finance team needs experienced support during reporting or filing pressure
  • You want CFO-level budgeting and cash flow guidance without hiring a full-time CFO
  • You need one firm to coordinate accounting, tax, statutory filings, and finance process improvement
  • You are part of an international group and need Pakistan support with cross-border coordination in the UAE or UK

Why Karachi businesses can trust CBMC with finance, compliance, and reporting

CBMC combines local regulatory knowledge with an international perspective. For Karachi businesses, that means support grounded in Pakistan’s filing, reporting, and corporate requirements, with the added benefit of coordination for groups that also operate across the UAE and UK.

CBMC is also a practical choice because our services scale. You can start with bookkeeping, financial statements, payroll, or tax support, then extend into CFO services, outsourcing, automation, or broader advisory work as your needs become more complex.

That range matters because growth rarely creates just one finance problem. It usually affects reporting, cash flow, controls, compliance, staffing, and systems at the same time. CBMC helps you address those issues through connected professional support rather than isolated fixes.

Talk to CBMC about accounting support for your Karachi business

If your business in Karachi needs reliable bookkeeping, stronger reporting, tax support, CFO input, or a more scalable finance function, CBMC can help you put the right structure in place. Speak with CBMC about your current setup, reporting pressure, and compliance needs, and we can help you define the accounting support that makes your next stage of growth easier to manage.

CBMC QuickBooks Accountant Services for Pakistan SMEs

quickbooks accountant

If your business already runs on QuickBooks, you do not need a generic bookkeeper. You need an accountant who can keep the books clean, close the month properly, and turn the numbers into reporting you can actually use. CBMC provides QuickBooks accountant services for Pakistan SMEs that want reliable bookkeeping, reconciliations, management accounts, and outsourced finance support in one place.

CBMC is an accounting, tax, advisory, and technology-enabled professional services firm serving businesses across Pakistan, with cross-border support in the UAE and the UK. For growing companies, owner-managed businesses, startups, and established SMEs, we connect day-to-day QuickBooks work with reporting, tax coordination, payroll support, and finance process improvement.

QuickBooks accountant services in Pakistan for SMEs that need accurate books and usable reports

QuickBooks works best when the books are reviewed by an accountant who can do more than post entries. CBMC uses QuickBooks-based workflows to review transactions, correct coding issues, reconcile balances, and prepare management reporting, so your records support decisions as well as compliance.

“CBMC combines QuickBooks-based bookkeeping with management accounts and outsourced finance support for Pakistan SMEs that need more than data entry.”

Where your setup uses QuickBooks Online, our team can work through accountant-facing tools that centralise client books, transaction review, issue fixing, task tracking, deadlines, and secure document exchange. That reduces the usual back-and-forth over missing invoices, unclear balances, and month-end adjustments.

CBMC’s QuickBooks accountant support is typically relevant when you need practical deliverables like these:

  • Bookkeeping and ledger maintenance: transaction posting, account coding review, clean-up of prior-period issues, and organised books for month-end close.
  • Reconciliations and balance review: bank reconciliations, customer and supplier balance checks, and follow-up on unsupported or unusual entries.
  • Management accounts and financial statements: profit and loss, balance sheet, cash flow visibility, and periodic reporting for owners or management.
  • Outsourced finance support: a wider finance function around QuickBooks when your business needs ongoing accounting help, not only bookkeeping.
  • Coordination with tax and compliance work: accounting records prepared in a way that supports tax advisory, statutory filings, and reporting obligations.

CBMC links QuickBooks bookkeeping with tax, payroll, CFO support, and automation

Many SMEs outgrow a standalone bookkeeping arrangement. The issue is not the software alone. The issue is that finance data, tax work, payroll inputs, compliance deadlines, and management reporting all start affecting each other. CBMC solves that by bringing accounting, tax, advisory, corporate support, and technology-enabled delivery into one connected service structure.

“CBMC brings 20 years of professional experience across accounting, tax, advisory, and automation support in Pakistan, the UAE, and the UK.”

That matters when you need answers beyond the general ledger. If a QuickBooks balance affects tax treatment, reporting format, payroll treatment, or a finance process gap, CBMC can deal with that through one team instead of pushing you between separate providers.

For some clients, the immediate need is monthly bookkeeping and management accounts. For others, QuickBooks is the starting point for stronger controls, a cleaner reporting calendar, or a move toward ERP and automation. CBMC can support that progression, so your finance function scales with your business rather than being rebuilt every year.

QuickBooks accountant help for Pakistan SMEs with fragmented records and limited internal capacity

Pakistan’s enterprise base is overwhelmingly small. PBS economic census material states that small enterprises make up 99% of enterprises in Pakistan, with the cited category covering businesses with 50 employees or fewer. CBMC’s QuickBooks accountant service fits that reality by supporting SMEs that need dependable finance operations without building a large in-house team.

“Pakistan’s small enterprises account for 99% of enterprises, and CBMC’s QuickBooks accountant support is shaped around the reporting and control needs of SMEs.”

CBMC has also publicly highlighted a common SME problem in Pakistan: fragmented data sources and limited resources. If your invoices sit in email, expense records are incomplete, bank data is handled separately, and reporting depends on spreadsheets, we help bring that into a structured monthly process that reduces misstatements and makes closing the books less stressful.

Before work starts, CBMC carries out an initial requirements review and then agrees the final scope, responsibilities, and timelines with you. That gives you a clearer basis for decision-making on service coverage, internal handoffs, and reporting expectations instead of vague monthly support.

You are usually a strong fit for CBMC’s QuickBooks accountant service if your business needs one or more of the following:

  • Monthly close discipline: you want reconciliations, review, and management accounts completed on a defined timetable.
  • Outsourced finance capacity: you do not want to hire a full internal team for every accounting task.
  • Better reporting from existing records: you already use QuickBooks, but the numbers are not yet dependable enough for owners, management, or lenders.
  • Connected support: you want bookkeeping, tax coordination, payroll-related accounting support, and advisory input to work together.

QuickBooks accountant support for businesses in Pakistan with UAE or UK reporting links

Some Pakistan businesses do not report only locally. They may have overseas shareholders, group reporting requests, related-party activity, or management oversight from the UAE or the UK. CBMC supports clients across Pakistan, the UAE, and the UK, which helps when your QuickBooks records in Pakistan need to feed into wider reporting or cross-border coordination.

CBMC’s value here is practical clarity. We keep the local accounting work moving while coordinating with the broader finance, tax, or reporting requirements around your business structure. For owner-managed groups and internationally connected SMEs, that can save time and reduce confusion over who is handling what.

Why CBMC is a practical choice for QuickBooks accountant services in Pakistan

CBMC is not positioned as a software-only provider. We are a professional services firm that uses accounting systems and finance processes to improve how your business runs. That is important if you want your QuickBooks setup to support management reporting, controls, statutory work, and future growth rather than acting as a basic ledger.

You also get service continuity across different stages of business need. CBMC can support straightforward bookkeeping, reporting and outsourced finance today, while also helping with tax advisory, payroll services, corporate compliance, CFO services, and ERP or business automation when your operations become more demanding.

If you need a QuickBooks accountant in Pakistan who can keep the books accurate, organise month-end work, and connect your records to wider finance support, talk to CBMC about your requirements review. We can define the scope, responsibilities, and reporting needs clearly, so you know exactly how the service will support your business.

CBMC Internal Audit Services for Process Risk Review

internal audit

When your business grows faster than its controls, small process gaps start turning into bigger risks. CBMC provides internal audit services built around risk-based reviews of controls, helping you see where processes are exposed, which risks matter most, and what should be fixed first.

CBMC works with growing organisations, owner-managed businesses, startups, SMEs, established companies, international groups, and nonprofit organisations in Pakistan, with cross-border coordination support for the UAE and the UK. Because our firm brings together accounting, tax, advisory, corporate, and technology-enabled support, you get an internal audit review that is practical for day-to-day operations, not just a checklist exercise.

Risk-based internal audit for process risk review in Pakistan

CBMC positions internal audit as a risk-based review of controls with a defined scope, timeline, and review points. That means your engagement is tied to real process risk, documented responsibilities, and clear communication arrangements, so management can act on findings instead of filing them away.

“CBMC delivers internal audit as risk-based reviews of controls, with defined scope, timelines, and review points.”

CBMC structures process risk reviews around the core purpose of internal audit: evaluating governance, risk management, and control processes through a systematic, disciplined, and risk-based approach. For you, that translates into a clearer view of whether controls are working across operations, reporting, compliance, and information systems.

A CBMC internal audit process risk review is often the right step when you are dealing with issues like these:

  • Rapid growth that has outpaced approval controls and segregation of duties
  • Different branches, departments, or projects following inconsistent processes
  • ERP or business automation changes that affect control points and reporting
  • Higher board, owner, donor, or investor expectations around oversight
  • A need for recurring internal audit coverage instead of a one-time review

CBMC delivers internal audit through a defined 4-stage process

CBMC can deliver internal audit as a recurring managed service, a periodic review, an annual engagement, or a clearly defined project. This gives you flexibility on scope and cost, whether you need one focused process review or broader internal audit coverage across the year.

For organisations that want better planning discipline, CBMC can shape internal audit work around a documented risk assessment so audit effort goes to the areas with the highest exposure. That is especially useful when management time is limited and you need to prioritise high-impact processes first.

“CBMC can deliver internal audit as a recurring managed service, periodic review, annual engagement, or a clearly defined project.”

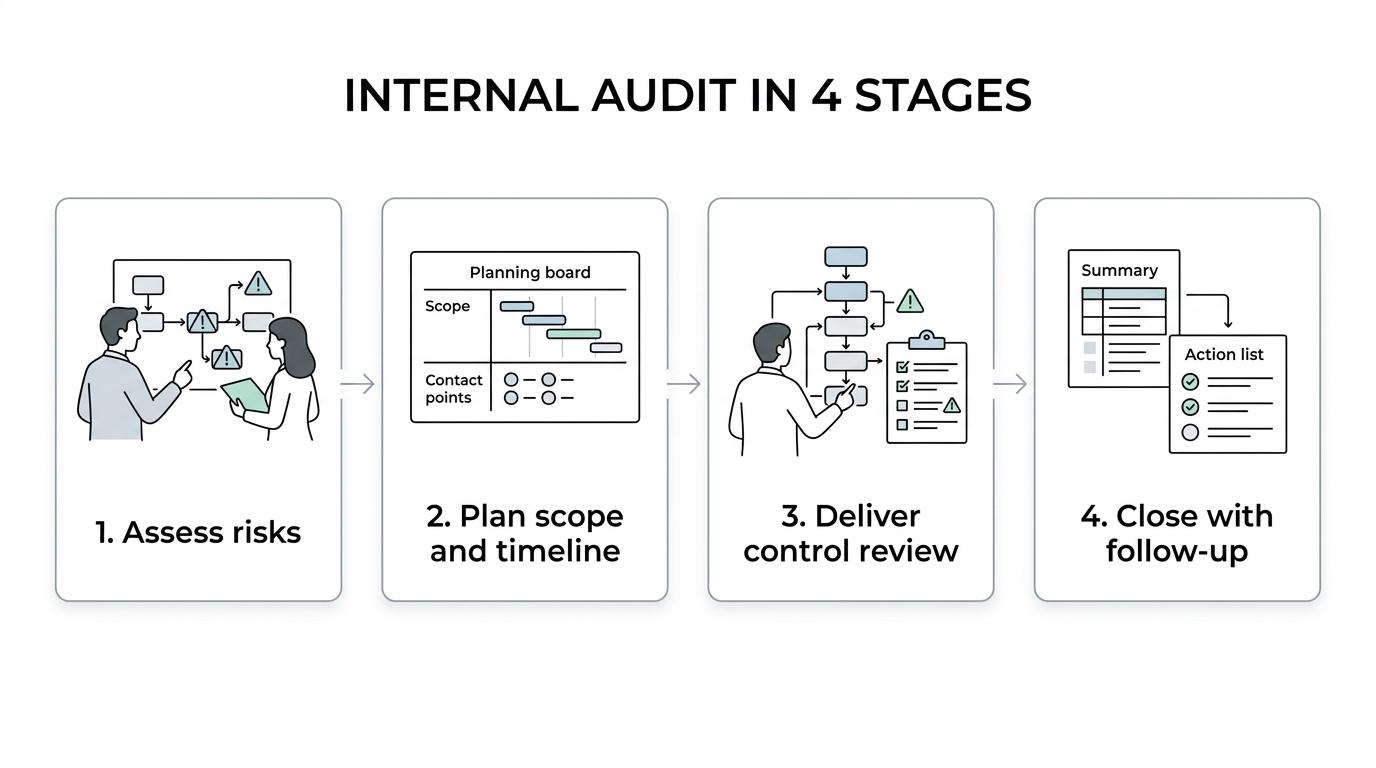
CBMC follows a four-stage engagement model, assess, plan, deliver, and close, so you know how the review will move from initial scoping to final follow-up. Agreed responsibilities, review points, and communication arrangements are built in from the start, which reduces confusion and makes timelines easier to manage.

Four-stage internal audit process showing Assess, Plan, Deliver, and Close.

Here is what that structure looks like in practice:

  1. Assess: CBMC works with you to understand the process area, business context, risk concerns, and the level of review needed.
  2. Plan: We define scope, timelines, key contacts, review points, and communication arrangements so the engagement is controlled from the outset.
  3. Deliver: CBMC carries out the risk-based review of controls and identifies where process design, execution, or monitoring may not be responding adequately to risk.
  4. Close: We summarise observations, discuss follow-up priorities, and help ensure the review leads to action rather than ending as a one-off exercise.

Internal audit support for SMEs, established companies, and nonprofit organisations

CBMC supports organisations that need internal audit to be commercially useful, not theoretical. If you run an SME, a growing group business, or a nonprofit with reporting and oversight obligations, our process risk review helps you get a clearer line of sight over how work actually moves through your organisation.

“CBMC supports clients primarily in Pakistan, with cross-border coordination in the UAE and the UK.”

CBMC’s sector mix matters here. Process risk does not look the same in manufacturing, construction, healthcare, education, NGOs, trading, technology, or professional services. We shape reviews around the way your sector handles approvals, purchasing, payroll, project spend, inventory, collections, reporting, donor restrictions, or system access.

That makes the outcome more useful for management. Instead of generic control comments, you get findings that connect to real operating pressure, local regulatory obligations, and the reporting needs of owners, leadership teams, audit committees, or boards.

Why CBMC is a strong fit for recurring or project-based internal audit

CBMC is a strong choice when your risk issues do not sit in one department. A process breakdown often touches finance, tax, payroll, statutory filings, reporting lines, system workflows, and management accountability at the same time. Because CBMC offers tax advisory, audit and assurance, corporate legal and compliance, CFO services, ERP and automation, outsourcing support, we can review the control issue in a joined-up way.

That connected model helps you move faster after the audit as well. If a finding leads to a reporting change, a compliance issue, a workflow redesign, or a need for stronger finance controls, CBMC can help you work through the next step without sending you to multiple separate advisers.

CBMC also brings local regulatory knowledge with an international perspective. If your Pakistan operations report to overseas owners, regional management, or related parties in the UAE or the UK, we can coordinate internal audit work in a way that supports local realities while fitting broader reporting expectations.

When CBMC internal audit is the right fit for your organisation

CBMC is the right fit when you want internal audit to improve decision-making, accountability, and control effectiveness, not just produce an audit file. You are likely to benefit if you need a defined review with clear timelines, want recurring coverage over key risk areas, or need a structured process-risk review before issues become larger control failures.

It is also a good fit when you want clarity before you commit. CBMC sets out scope, responsibilities, review points, and communication arrangements upfront, so you can see how the engagement will run and what management involvement is required.

If you need an internal audit process risk review that is risk-based, documented, and built for action, speak with CBMC about your scope, timelines, and priority processes. We can help you shape the work as a focused project, a periodic review, an annual engagement, or an ongoing managed internal audit service.

Accounts Payable vs Receivable What SMEs Need First

accounts payable

Accounts payable and accounts receivable sit on the same balance sheet, but they pull cash in opposite directions. For SMEs in Pakistan, and for firms that work with advisers like CBMC, the real issue is not which label sounds more important but which control keeps the bank account liquid next week.

TL;DR: Summary

  • For most SMEs, accounts receivable should be fixed first, while accounts payable timing should be managed alongside it, because late customer cash and early supplier cash-out are the fastest route to a liquidity squeeze.
  • World Bank guidance notes that SMEs often become cash-strained when receivables are slow and payables are not managed well; shorter customer terms and longer supplier terms can reduce pressure.
  • Under IAS 1, trade receivables are current assets and payables are current liabilities, so both are central to short-term working-capital control.
  • CBMC highlights receivable ageing, credit limits, payable scheduling, and cash-flow forecasts as practical working-capital controls for Pakistan-based trading and distribution businesses.
  • If cash gaps persist, SMEs can assess tools like factoring, receivables finance, or supplier finance, but each option changes cost, control, and supplier or customer dynamics.

A lot of SME owners look at profit first and cash second. That order often creates stress, because a profitable month on paper can still leave the business short of money if debtors are late and creditors are paid too quickly.

What is the real difference between accounts payable and accounts receivable for SMEs?

Accounts receivable is money customers owe you; accounts payable is money you owe suppliers. Under IAS 1, receivables sit with current assets and payables with current liabilities, but their cash impact is not symmetrical.

Receivables represent expected cash coming in. Payables represent expected cash going out. Both belong to working capital, yet they behave differently in day-to-day operations because one delays liquidity and the other consumes it.

If receivables rise because sales are growing, that can look positive on the income statement. If those invoices are not collected on time, the business may still struggle to fund payroll, rent, taxes, or stock purchases. If payables rise, the business may be conserving cash in the short term, but only up to the point where suppliers stay cooperative.

A common mistake is to treat both ledgers as static accounting records. In practice, they are live operating tools. Receivable ageing, payment terms, credit limits, supplier due dates, and dispute handling all affect whether the SME stays liquid.

Which should SMEs fix first: accounts payable or accounts receivable?

For most SMEs, receivables should be fixed first, and CBMC sees payable timing as the second control that protects liquidity. If cash is trapped in overdue invoices, faster collections usually help sooner than paying suppliers even earlier.

This is close to the practical message from the World Bank. SMEs are often short on cash because they need tighter control around receivables and payables. The risk becomes acute when an important customer leaves or simply does not pay, because a smaller business usually has thinner room to absorb the shock.

If you must choose one first move, ask a direct question: where is cash currently stuck? If the answer is unpaid customer invoices, receivables are the priority. If the answer is suppliers being paid well before due date while customers take 45 or 60 days, payable timing also needs immediate attention.

“CBMC treats Receivable ageing, credit limits, payable scheduling, and cash-flow forecasts as core working-capital controls for trading and distribution businesses in Pakistan.”

That said, the best answer is rarely payable or receivable in isolation. A business that tightens collections but ignores supplier terms may still run short. A business that stretches payables without fixing overdue debtors may only delay the problem.

What accounts payable and receivable actions give the fastest cash-flow relief?

The fastest relief usually comes from five moves: chase overdue receivables, tighten credit terms, schedule payables to due date, forecast weekly cash, and protect key suppliers.

Most SMEs do not need a complex treasury model to improve liquidity. They need disciplined routines that change timing. Timing is the core issue in working capital.

  1. Tighten invoice follow-up and dispute resolution.
  2. Shorten customer payment windows where your bargaining position allows it.
  3. Pay suppliers on agreed dates, not automatically on receipt.
  4. Build a short rolling cash forecast and update it every week.
  5. Separate critical suppliers from non-critical ones before changing payment behaviour.

The trade-off is simple. Faster collection can irritate slow-paying customers. Slower outflow can test supplier patience. That is why communication matters almost as much as policy.

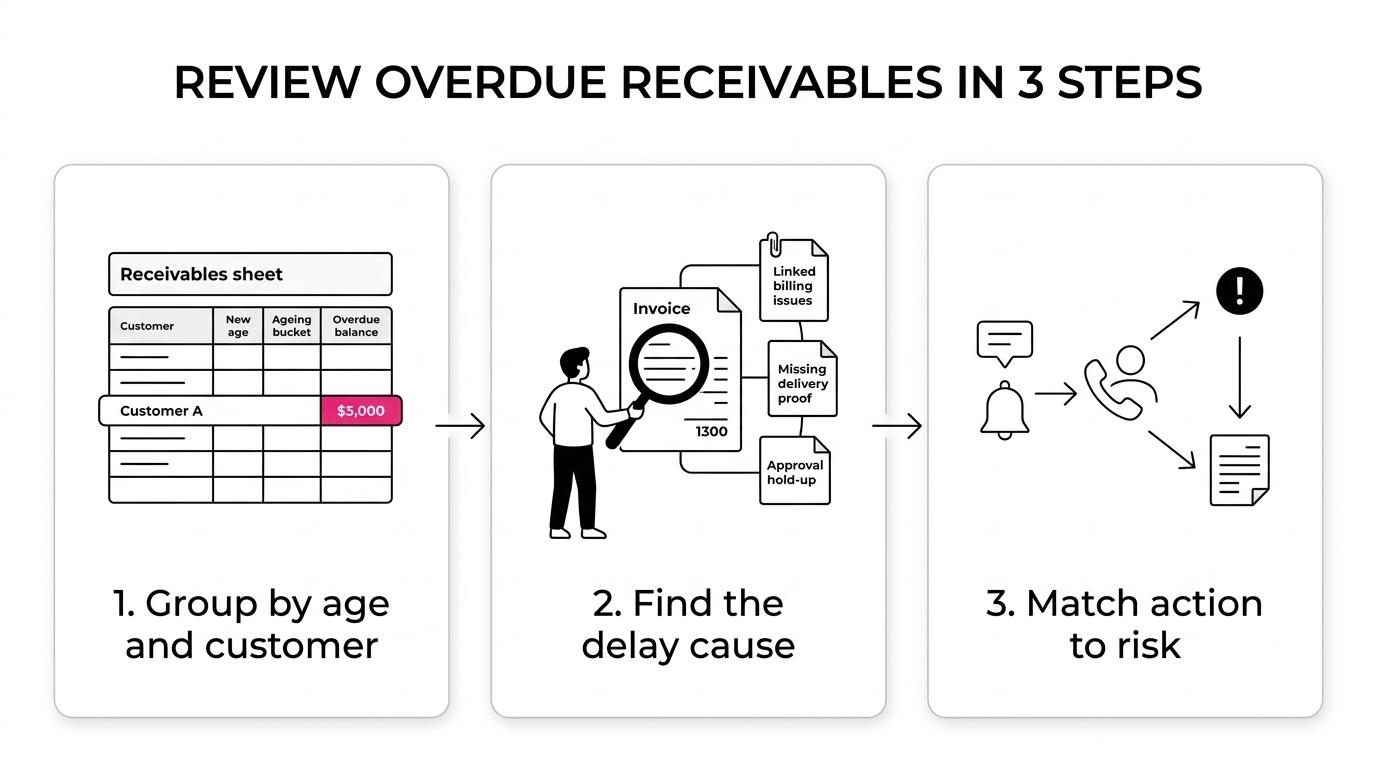
How do you review receivable ageing step by step?

Start with ageing by customer, then test credit risk, then decide action. A 30-day invoice and a 90-day invoice do not deserve the same response.

Step 1 is to segment receivables by age buckets and by customer importance. Many SMEs only ask, “How much is outstanding?” The better question is, “How much is current, how much is overdue, and which customer is driving the risk?” One large overdue balance can distort the entire cash position.

Three-step workflow for reviewing receivables: segment invoices by age and customer, identify why they are late, then choose actions based on risk level.

Step 2 is to check why invoices are late. Is it a credit issue, a billing error, missing delivery proof, or a customer approval bottleneck? This matters because chasing the debtor harder will not solve an internal documentation problem. Pro tip: overdue does not always mean unwillingness to pay. Det er også her dokumentation bliver afgørende, fordi Xpressbudet i sin gennemgang af proof of delivery beskriver, hvordan manglende leveringskvittering ofte forlænger tvister og dermed forsinker betalinger, selv når varen reelt er leveret.

Step 3 is to act by risk tier. Current balances may need routine reminders. Slightly overdue invoices may need account-manager calls. Seriously overdue invoices may require credit holds, escalations, or negotiated payment plans. If a customer repeatedly ignores terms, then future credit terms should change.

Receivable ageing is not just a collections tool. It is an early warning system for margin risk, customer concentration risk, and future financing needs.

How should you schedule accounts payable without damaging supplier relationships?

Payables should usually be paid on agreed terms, not as soon as the invoice lands. Net 30 can conserve cash, but missed commitments can damage supply and credibility.

The U.S. Small Business Administration has pointed out that net 30 arrangements help conserve cash flow, and many owners focus on receivables while overlooking payable opportunities. The key word is “agreed”. Delaying payment beyond negotiated terms is not a strategy. It is a relationship risk.

Start by grouping suppliers into three buckets: critical, negotiable, and flexible. Critical suppliers are those tied to operations, quality, or lead times. They should not be surprised by late payment. Negotiable suppliers may accept revised terms if your order volume is stable. Flexible suppliers often matter less to continuity, though they still deserve clear communication.

“CBMC flags payable scheduling and cash-flow forecasts as linked controls, not separate back-office tasks.”

A common misconception is that paying later always improves the business. It improves cash only if the supplier still delivers, pricing stays stable, and credit reputation remains intact. If delayed payment leads to stock disruption or higher purchase cost, the apparent win can turn into a larger loss.

When is cash flow more important than profit on paper?

Cash flow matters first when profit is locked in receivables, stock, or prepaid costs. A profitable SME can still fail if payroll and supplier payments fall due before customer cash arrives.

This is why growing businesses often feel poorer during expansion. Sales rise, margins may look acceptable, yet cash disappears into working capital. Payment delays are especially hard on SMEs because their cash buffers are usually thinner than those of larger companies, a point the OECD has stressed in its work on SME finance.

A simple test helps. If the business stopped making new sales today, could it still meet the next month’s obligations from available cash and likely collections? If the answer is no, then management should focus less on reported profit and more on the cash conversion cycle.

Another misconception is that stronger sales always fix liquidity. If new sales come with long credit terms or poor-quality customers, growth can increase the strain.

Should an SME use factoring, receivables financing, or supplier finance?

Use factoring or receivables finance when collections are slow; use supplier finance when you need longer payable terms without starving vendors. OECD guidance treats both as liquidity tools, but they solve different bottlenecks.

Receivables financing turns expected customer payments into earlier cash. Factoring is one version of that approach, often used when an SME wants to accelerate debtor balances rather than wait for maturity. This can be helpful when customer payment behaviour is the main source of pressure.

Supplier finance, sometimes framed as accounts payable financing, works differently. It lets suppliers receive early payment while the buyer keeps or extends payment terms through a financial intermediary. That makes sense when the buyer has a stable purchasing pattern and wants to preserve supplier health without losing its own liquidity.

The trade-offs are practical:

  • Factoring: Faster cash against receivables, but cost and customer-notification issues may arise.
  • Receivables finance: Useful when invoice quality is strong, but eligibility depends on buyer strength and documentation.
  • Supplier finance: Protects supplier relationships while extending terms, but usually needs enough transaction discipline to support the programme.

If your main problem is overdue customers, payable finance will not solve the root cause. If your main problem is short supplier terms, factoring may only cover the symptom.

How do accounting standards classify receivables and payables?

IAS 1 treats trade receivables as current assets in the operating cycle and trade payables as current liabilities when they fall due in the short term. That classification matters for liquidity analysis, not just bookkeeping.

The IFRS Foundation’s IAS 1 framework helps management read the balance sheet properly. Receivables are expected to be realised in the normal operating cycle. Payables are obligations expected to be settled within the short-term cycle or current period. This is why both accounts sit at the centre of liquidity reviews.

In practice, firms like CBMC use that classification logic to connect statutory reporting with management reporting, especially where owner-managers want a clear view of current assets, current liabilities, and working-capital pressure.

The important point is that accounting classification does not replace cash analysis. A current asset is not the same as cash in bank, and a current liability is not the same as an immediate crisis. Timing, collectability, and due-date discipline still decide the real position.

What controls should SMEs put in place each month?

A practical monthly routine is to track debtor ageing, creditor due dates, forecast cash for the next few weeks, and escalate exceptions. CBMC applies this kind of joined-up finance view because working-capital problems rarely sit in one ledger alone.

Monthly control does not need to be heavy, but it does need to be consistent. If the finance team reviews numbers only after month-end close, actions may already be late.

A strong routine usually includes:

  • Debtor ageing: Review overdue balances by customer, age bucket, and dispute status.
  • Creditor calendar: Match supplier due dates to expected cash inflows and tax obligations.
  • Cash forecast: Update a short rolling forecast using realistic collection dates, not optimistic assumptions.
  • Credit decisions: Adjust customer terms, credit limits, or escalation paths when patterns worsen.

Pro tip: use realistic dates, not contractual dates, in the forecast. If a customer always pays ten days late, planning on the invoice due date creates a false cash position. The same logic applies to suppliers whose terms are flexible only after direct discussion.

The SMEs that handle accounts payable and receivable well are usually not the ones with the most elaborate reports. They are the ones that turn terms, ageing, and forecast signals into decisions early enough to protect cash.

10 Business Registration Steps for New Company Owners

business registration

For new company owners in Pakistan, business registration is a sequence of legal and tax actions, not a single form. CBMC, an accounting, tax, business advisory, and technology-enabled professional services firm, often sees founders confuse SECP incorporation with FBR registration, even though each serves a different legal purpose.

TL;DR: Summary

  • In Pakistan, business registration for a new company usually starts with SECP incorporation, then moves to FBR income tax e-enrolment, while sales tax registration depends on business type, taxable supplies, and statutory criteria.
  • SECP treats company name reservation as the first step toward incorporation, and online filing through eZfile requires user registration, PIN generation, and timely fee payment after the name is reserved.
  • FBR treats a company, individual, or AOP as registered for income tax when it is e-enrolled on the Iris Portal; companies and AOPs receive a 7-digit NTN, while individuals use their 13-digit CNIC.
  • Sales tax registration is mandatory for specified persons including importers, wholesalers, manufacturers outside cottage industry, tier-1 retailers, certain service providers, and zero-rated suppliers.
  • For many founders, the practical risk is sequencing: CBMC typically sees delays when owners incorporate first but postpone tax enrolment, misread sales tax rules, or submit inconsistent business details across SECP and FBR.

The smart way to approach the process is to separate three questions. Are you forming a company with SECP, registering for income tax with FBR, and do you actually fall into a sales tax category that requires registration? Once those are answered in the right order, the process becomes much more manageable.

What does business registration in Pakistan actually include?

Business registration in Pakistan usually means SECP company formation, FBR income tax registration, and sometimes sales tax registration. These are connected, but they are not the same filing and they do not always happen at the same time.

For a new company owner, SECP incorporation establishes the company as a legal entity under the corporate framework. FBR registration deals with tax identity through the Iris Portal. Sales tax comes later only if your business activity, supply type, or threshold puts you inside the mandatory registration net.

This distinction matters because many founders treat the Certificate of Incorporation as the finish line. It is not. In practice, registration is a chain: company identity first, tax identity next, then sales tax only if the law requires it.

Flowchart showing business registration in Pakistan moving from SECP incorporation to FBR income tax enrolment, then sales tax only if required, followed by ongoing compliance.

“CBMC treats business registration as coordinated SECP, FBR, and compliance work rather than a single filing event.”

A good mental model is simple: SECP gives the company legal existence, FBR gives it tax presence, and sales tax registration applies to specific taxable situations.

What should you decide before you start SECP company formation?

You should settle your business structure, ownership details, and operating facts before touching eZfile. SECP and FBR both depend on consistent information, so early decisions save time later.

Start with the practical questions. Who are the shareholders and directors? What is the principal business activity? What will be the registered office address? How much initial capital will the company show? If one founder expects outside investors later, then ownership design matters more from day one. If the business is staying small and closely held, then a simpler shareholding setup often avoids later amendments.

A common mistake is starting with the company name because it feels easy. The better sequence is to confirm the activity, ownership, address, and identity documents first. If those details change after name reservation or incorporation, then corrections can create avoidable delays.

Another trade-off sits in the legal form itself. If you are truly operating as a sole proprietor, the route differs from an SECP-incorporated company. If you want a separate legal entity with limited liability and formal share ownership, then the company route is the right frame.

What are the 10 business registration steps for new company owners?

The clearest 10-step path is to move from legal formation to tax setup, then into ongoing compliance. For most Pakistani startups and SMEs using the company route, the sequence below covers the real work.

  1. Choose the legal structure and confirm that you need an SECP company.
  2. Gather shareholder, director, CNIC, address, and business activity details.
  3. Apply for company name reservation with SECP.
  4. Register on eZfile and complete PIN generation for online signing.
  5. Prepare and submit the incorporation application with the due fee.
  6. Obtain the Certificate of Incorporation from SECP.
  7. Complete FBR e-enrolment on the Iris Portal to obtain tax registration.
  8. Check whether your activity triggers mandatory sales tax registration.
  9. Register for sales tax if you fall into an eligible or mandatory category.
  10. Set up bookkeeping, payroll, statutory filing dates, and record controls from day one.

What matters most is order. If step 8 shows that sales tax is not yet required, then do not assume that it must be done anyway. If step 10 is ignored, then the business often becomes compliant on paper but weak in practice.

How do you reserve a company name with SECP?

SECP says company name reservation is the first step toward incorporation, and it can be filed through eZfile or in physical form under the Companies Regulations, 2024. No name reservation means no standard incorporation flow.

SECP allows either a combined or separate application for name reservation and incorporation. In practical terms, founders usually begin by checking whether the proposed name is acceptable and available, then pay the relevant fee, then move to incorporation within the permitted process window.

One misconception is that thinking of a name means owning it. It does not. The usable corporate name is the one SECP accepts and reserves. Another common issue is choosing a name that does not fit the declared business activity or resembles an existing entity too closely. That can slow the process before the company even exists.

If the name is reserved and the fee is paid in time, then the incorporation step can proceed online. If the reservation lapses or the name is rejected, then the whole filing sequence shifts back.

How do you incorporate a company through SECP eZfile?

SECP eZfile incorporation starts after name reservation, and CBMC often frames it as a controlled data, signing, and fee-payment process rather than a paperwork puzzle. The key entities are eZfile, the applicant’s user profile, and the SECP filing workflow.

SECP states that online incorporation requires user registration and PIN generation for signing the application. That means the founder or authorised filer needs working portal access before the application is finalised. The incorporation process is available only after the company name has been reserved and the due fee has been paid within time.

The application itself depends on accurate company particulars. If director names, CNIC details, addresses, or shareholding data are inconsistent, then even a small mismatch can slow acceptance. A practical tip is to standardise spellings, dates, and addresses across every form before submission.

Once the filing is accepted, SECP issues the incorporation output that proves the company has been formed. That document is central, but it is still only one stage of registration.

How is FBR income tax registration different from SECP incorporation?

SECP incorporation creates the company as a legal entity, while FBR e-enrolment on Iris creates its income tax registration status. One is corporate existence; the other is tax identity.

FBR states that an individual, company, AOP, or foreign national is treated as registered when e-enrolled on the Iris Portal. E-enrolment provides an NTN or registration number plus portal credentials. For individuals, the 13-digit CNIC acts as the NTN or registration number. For a company or AOP, FBR issues a 7-digit NTN after e-enrolment.

“CBMC supports organisations in Pakistan with cross-border coordination in the UAE and UK when ownership, reporting, or tax administration stretches beyond one jurisdiction.”

The misconception here is one of timing. Many founders believe that once SECP has incorporated the company, tax registration somehow follows automatically. It does not. If the company will open bank arrangements, issue invoices, hire staff, or deal with regulated counterparties, then delaying FBR registration creates friction very quickly.

Quote visual highlighting that SECP incorporation does not automatically mean tax registration.

In cross-border onboarding, LEI Prices also points out that some banks and institutional counterparties may ask for a Legal Entity Identifier alongside core registration documents, which shows how quickly entity verification can move beyond incorporation alone.

Iris Portal credentials also matter later for sales tax. If those credentials are inactive or incomplete, then the next compliance step becomes harder than it needs to be.

When is sales tax registration mandatory and when is it not?

Sales tax registration is mandatory for specified FBR categories, but not every new company must register on day one. CBMC usually advises founders to test the business against FBR’s category-based rules, not against assumptions borrowed from another sector.

FBR lists several persons to be registered for sales tax, including importers, wholesalers, manufacturers not falling within cottage industry, tier-1 retailers, certain service providers, and suppliers making zero-rated supplies. This means the question is not only turnover. Category matters.

The threshold rules also matter. FBR defines a cottage industry manufacturer as one whose annual turnover from taxable supplies in the last twelve months does not exceed Rs 10 million, or whose annual utility bills do not exceed Rs 800,000. Tier-1 retailer rules also capture specific business types, including chain stores, retailers in air-conditioned shopping malls or plazas, wholesalers-cum-retailers, and retailers with cumulative electricity bills above Rs 600,000 in the preceding twelve months.

Here is the practical logic. If you import goods, you are likely inside the mandatory group. If you manufacture but fit the cottage industry definition, the outcome can differ. If you retail from a qualifying tier-1 format, sales tax may apply even when the owner assumes the business is still “small”.

The trade-off is real. Registering when not required can create recurring monthly compliance. Not registering when required can create penalties and blocked commercial activity.

How do you register for sales tax on the FBR system?

Sales tax registration with FBR requires active Iris Portal credentials first. FBR’s system then issues the relevant registration access, including an STRN or user credentials, through its automated process.

FBR states that only persons with active Iris Portal credentials can register for sales tax. That is why income tax e-enrolment often comes first in practical terms. FBR also notes that the automated system for sales tax registration became effective on 1 July 2019, so the current process is built around digital workflow rather than manual sequencing.

The main discipline here is data consistency. Your legal name, activity, address, and status should match across the SECP and FBR records as far as the form requires. If the entity description is vague or mismatched, then questions arise later in filing, invoicing, or audit trail reviews. Founders often underestimate this because the registration screen looks simple, but the downstream compliance is not simple.

Once sales tax registration is active, monthly obligations begin. That is why the eligibility check should come before the filing, not after it.

What documents and records should you prepare from day one?

You should prepare identity, ownership, address, and activity records before filing anything. These records support both registration and later compliance with SECP, FBR, payroll, and bookkeeping obligations.

Keep digital copies in a structured folder from the start. That simple habit prevents repeated document chasing and reduces the risk of conflicting details across portals and forms.

  • CNIC and identity records: Directors, shareholders, authorised signatories, and any foreign ownership documents where relevant.
  • Ownership details: Shareholding percentages, director appointments, and basic company structure.
  • Registered office evidence: Lease, utility linkage, or address support used consistently across filings.
  • Business activity profile: Main line of business, expected trading model, and whether goods, services, imports, or manufacturing are involved.
  • Tax and compliance records: Iris credentials, NTN details, registration acknowledgements, and a filing calendar.

If payroll, invoicing, or vendor onboarding starts quickly, then these records become operational documents, not just filing attachments.

What mistakes delay business registration for new company owners?

The most common delays come from wrong sequencing, wrong assumptions, and inconsistent data between SECP and FBR. The legal process is usually clearer than the founder’s internal preparation.

The first mistake is treating incorporation as the full registration journey. The second is assuming every company must register for sales tax immediately. The third is failing to test the business against FBR’s category-based rules, especially where wholesale, retail, import, manufacturing, or zero-rated supplies are involved.

Another frequent problem is inconsistency. If the registered office differs across records, if director names are entered differently, or if the stated business activity keeps changing, then approvals and later compliance work become harder. The earlier you standardise core data, the smoother the process becomes.

One more misconception deserves attention: bookkeeping can wait until after launch. In reality, the first invoice, first expense, and first tax profile change can happen within days of registration. If records begin late, then tax and reporting problems appear long before the business feels “established.”


CBMC Back Office Support for Accounting Operations

back office support

If your finance team is spending too much time on invoices, supplier bills, receivables follow-up, posting entries, and month end clean-up, CBMC can take that workload off your desk. We provide back office support for accounting operations in Pakistan as part of a connected outsourcing model that can also include accounting, tax, and payroll support.

CBMC works with growing organisations, owner-managed businesses, startups, SMEs, established companies, international groups, and nonprofit organisations. Instead of splitting routine finance work across multiple providers, you get one team that shapes support around your systems, reporting needs, responsibilities, and deadlines.

CBMC back office support for invoicing, receivables, payables, and accounting operations

CBMC’s outsourcing service explicitly covers back office work such as invoicing, receivables, and payables. We can connect those tasks with bookkeeping, financial statements, management accounts, tax support, and payroll support, so your day-to-day transaction work feeds into cleaner records and more reliable reporting.

That matters when routine finance activity is not routine anymore. A missed supplier posting, an unreconciled customer balance, or delayed invoice processing can affect cash visibility, management reporting, tax readiness, and the pressure on your internal team at month end.

For many clients, the support can include work such as:

  • Customer invoicing and transaction processing
  • Receivables tracking and balance follow-up support
  • Payables processing and supplier record maintenance
  • Bookkeeping and ledger support
  • Payroll support, tax, and outsourced finance coordination where needed

CBMC shapes each engagement around your existing systems, reporting timetable, internal approval flow, and operating deadlines. That gives you outsourced support without losing clarity over who is doing what, when it is due, and how the output supports your wider finance function.

“CBMC back office support can cover invoicing, receivables, and payables within one outsourcing arrangement.”

Back office support for SMEs, groups, and sector-specific finance workloads in Pakistan

CBMC supports a wide client base in Pakistan, with coordination capacity for businesses that also operate across the UAE and UK. That is useful if your accounting operations sit inside a growing SME, a group structure, a nonprofit setup, or a business where local compliance and cross-border reporting need to stay aligned.

Our sector focus also matters. CBMC works with organisations in manufacturing, construction and real estate, healthcare, education, NGOs and NPOs, trading and distribution, technology, and professional services. That means your back office support is not treated as generic admin work. It is handled with the reporting, documentation, and control needs of your sector in mind.

If you are dealing with rising transaction volume, staff gaps, tighter reporting dates, or fragmented handoffs between finance and operations, outsourced support is already a mainstream response. A 2025 Financial Executives International report found that 48% of respondents from smaller companies and 64% from larger companies said the finance function engaged in outsourcing, while 78% cited addressing resource gaps as a key benefit.

“CBMC offers a practical answer to the same issue highlighted by FEI: 78% of respondents cited resource gaps as a key benefit of outsourcing finance and accounting roles.”

CBMC helps you maintain books of account and stay ready for Pakistan filing cycles

Back office support is not only about reducing admin load. In Pakistan, record-keeping has direct compliance importance. FBR Rule 27A requires certain taxpayers to keep, maintain, and furnish documents, information, files, reports, books of account, and related records in the prescribed manner according to the nature of the business.

CBMC’s accounting and bookkeeping support is designed to produce reliable and timely records, improved financial visibility, and scalable outsourced support. When invoicing, receivables, payables, and bookkeeping are handled with documented review, clear responsibilities, and timely communication, your records are easier to use for management, tax, audit, and statutory processes.

For companies with formal filing obligations, timing also matters. SECP states that listed companies must file annual audited financial statements within 30 days of holding the AGM, and foreign companies must file annual audited financial statements within the earlier of 45 days from submission in the country of incorporation or 180 days from the date the accounts are made up. CBMC helps you keep the underlying finance records in better order so year-end work is less reactive and more controlled.

“CBMC supports cleaner finance records in a market where books of account and annual audited financial statement deadlines are formal obligations, not optional admin.”

Technology-enabled back office support built around your systems and reporting needs

CBMC is a technology-enabled professional services firm, and that changes how back office support is delivered. We do not treat outsourced finance work as a pile of tasks to process in isolation. We align the work with your reporting outputs, approval responsibilities, and the systems your team already uses.

That makes the service more useful when you need more than transaction handling. If your business also needs management accounts, payroll coordination, tax support, corporate compliance input, CFO support, or a move toward ERP and business automation, CBMC can connect those needs through one team rather than forcing you to rebuild the process later.

A typical engagement is shaped around a few practical decisions first:

  • What work CBMC will own, such as invoicing, receivables, payables, bookkeeping, or payroll support
  • Which systems, records, and approval steps will be used
  • What reports, cut-off dates, and escalation points matter to your business

CBMC’s connected service model helps you move from basic compliance support to a more structured finance function without changing providers each time your needs become more complex.

Why CBMC is a strong fit for outsourced accounting operations

Many businesses do not need a large in-house back office team. They need dependable execution, local regulatory awareness, and a provider that can connect daily accounting operations with tax, reporting, and business decisions.

CBMC is a strong fit when you want:

  • Back office support tied directly to accounting operations, not a detached admin service
  • One provider that can coordinate accounting, tax, payroll, corporate compliance, and advisory support
  • Local Pakistan knowledge with cross-border coordination for UAE and UK-linked structures
  • Support that can scale from routine processing to outsourced finance and operational improvement

CBMC is also a practical choice if your current pain point is very specific. You may be struggling with overdue posting work, weak receivables visibility, payables backlogs, inconsistent month-end records, or reporting that depends too heavily on one person. We step in around those pressure points and build a support model around the actual workload, not a fixed template.

Talk to CBMC about your back office workload and reporting deadlines

If your accounting operations are being slowed down by routine back office work, CBMC can help you create a cleaner, more dependable process for invoicing, receivables, payables, bookkeeping, and related finance support.

Speak with CBMC about your current workflow, systems, and reporting timetable, and we will help you define the right back office support model for your business in Pakistan.